What you will see in this article
Most owners who inherit a property in Andorra try to sell it before having their ownership regularised. It is the most frequent mistake and the one that delays the transaction the most: without the acceptance of inheritance, there is no legal vendor. The buyer may appear, the price may be agreed, and the transaction still cannot be closed.
What follows is the correct sequence for selling an inherited property in Andorra, with the actual timeframes and the points where cross-border inheritances get most bogged down.
Step 1: Accept the inheritance before thinking about selling
The process begins with the formal acceptance of the inheritance before an Andorran notary. This applies whether the heir resides in Andorra or lives in Spain, France or any other European country.
The baseline documentation needed at this stage:
Documentation for accepting an inheritance
- Deceased's death certificate
- Will granted in Andorra or, if one does not exist, a certificate of last will and testament from the deceased's country of residence
- Identity documentation of all heirs
- Simple land registry extract for the property in the Land Registry of Andorra
If the testator had a will drawn up outside Andorra, its validity in the Principality should be verified through the Legal Portal of Andorra, since Andorran regulations specifically govern the recognition of foreign wills.
Assuming that the Spanish or French will is directly enforceable in Andorra without prior validation. It is not, and the validation process adds between 4 and 8 weeks to the total timeframe.
Step 2: Change of registered ownership
Once the inheritance has been accepted before a notary, the change of ownership must be registered at the Land Registry. Only at that point does the heir legally appear as the owner of the property and can initiate any sale process.
The indicative timeframe from the notary signing ranges between 2 and 6 weeks, depending on the workload of the registry and the documentary complexity of the inheritance.
If a buyer pushes to sign a reservation or deposit contract before the change of ownership is registered, it is advisable to structure the agreement with a suspensive clause making the transaction conditional upon registration. Without such a clause, the heir assumes a genuine legal risk. The article about reservation and deposit in Andorra detail how to draft that condition.
Step 3: The taxation that nobody calculates before setting a price
Selling an inherited property in Andorra has two distinct tax impacts that are worth calculating before setting the asking price on the market.
Tax on Capital Gains in Transfers of Real Estate Property
This tax is levied on the gain obtained between the acquisition value and the selling price. In the case of an inheritance, the acquisition value taken as a reference is the value declared in the deed of acceptance of the inheritance, not the original price paid by the deceased.
The tax rate is regressive: it starts at around 25% for sales made in the first year following acquisition and decreases progressively until it becomes exempt after 10 years of ownership, in accordance with the regulations available at the Legal Portal of Andorra.
If the beneficiary accepts the inheritance in 2025 and sells in 2026, they are taxed at the maximum rate on the difference between the value declared in the inheritance and the sale price. Declaring a low inheritance value to reduce inheritance tax can significantly increase the capital gains tax upon selling. This calculation must be done before signing the acceptance deed, not after.
Inheritance and Gift Tax
Andorra applies an inheritance tax whose rate varies depending on the degree of kinship with the deceased and the value of the inherited estate. Direct heirs (spouse, children) enjoy reduced rates or partial exemptions. Second- or third-degree heirs are taxed at significantly higher rates.
The specific regulations and applicable sections are available through the Government of Andorra.
Settling inheritance tax with a property valuation below market value to reduce the immediate tax burden, without calculating the impact on capital gains tax when it is sold. These are two connected taxes, and optimising one without considering the other results in a larger overall bill for the transaction.
The specific case of the heir not resident in Andorra
When the heir lives outside the Principality, the process of selling an inherited property in Andorra adds a layer of complexity that lengthens the timeframes and multiplies the necessary paperwork.
The critical issues in cross-border inheritances:
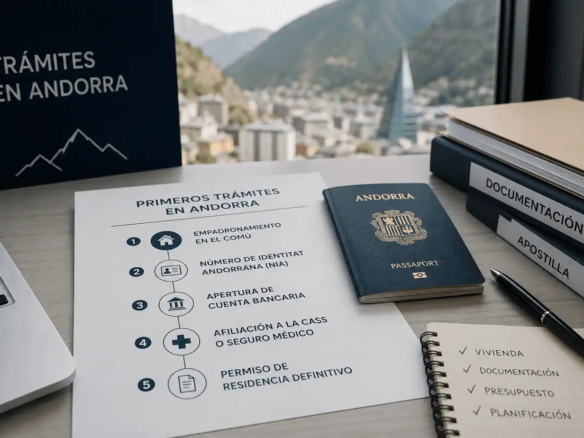
- Apostille of foreign documents. All documentation issued outside Andorra (death certificates, wills, powers of attorney) must be apostilled in accordance with the Hague Convention before it is valid before an Andorran notary.
- Representation in Andorra. If the heir is unable to travel to the Principality for each administrative procedure, they need to grant power of attorney to a local representative. That power of attorney must also be apostilled if it is granted abroad.
- Andorran bank account. The proceeds from the sale of a property in Andorra are usually settled through a bank account in the Principality. Opening an account as a non-resident requires specific documentation that should be arranged in parallel with the inheritance process, not at the end.
When it makes sense to sell and when to wait
Immediate sale is not always the most profitable decision. There are two scenarios where waiting significantly improves the financial outcome:
- If the inheritance is accepted with a high market valuation and the property is sold in under 10 years, the capital gains tax applies. In high-value properties in parishes such as Escaldes-Engordany o Andorra la Vella, that difference may be relevant.
- If the market is in a period of low demand, putting the property up for sale with urgency usually translates into price reductions that the heir would not need to take on with another month of leeway.
The property valuation before making the decision to sell, it allows that data to be on the table well in advance.
The next step
With the change of ownership registered and the tax calculated, the sales process can be structured with judgment. By sharing the parish where the property is located, the year the inheritance was accepted and the main characteristics of the property, the team at sales department prepare a reasoned valuation and a commercialisation plan that avoids the two most common mistakes: going to market too soon or doing so at a price that does not reflect the true value of the asset.
Frequently asked questions about selling an inherited property in Andorra
Can I sell an inherited flat in Andorra before accepting the inheritance?
No. Without formal acceptance of the inheritance before a notary and registration of the change of ownership at the Land Registry, the heir is not listed as the legal owner and cannot formalise any sale, even if there is a verbal agreement with a buyer.
How much tax is paid when selling an inherited property in Andorra?
Two different taxes apply: the Inheritance and Gift Tax upon accepting the inheritance (which varies according to family relationship and value) and Capital Gains Tax upon sale, which starts at around 25% in the first year of ownership and decreases progressively until it is exempt after 10 years.
How long does the whole process take if the heir does not live in Andorra?
In addition to the standard acceptance and registration period, a non-resident heir must factor in the time taken to apostille foreign documents (Hague Convention) and, in many cases, the opening of an Andorran bank account, which can add several additional weeks to the process.