What you will see in this article
- Which banks operate in Andorra and finance non-residents
- What really changes if you are not a resident
- Documentation they require: the actual list
- Three mistakes that block the mortgage before it even starts
- Mortgage and residency: the most frequent combination
- The next step
- Frequently asked questions
Andorran banks finance non-residents. However, the conditions shown on their website and those applied in practice do not always match. The percentage of funding decreases, the documentation required is more extensive than for a resident, and some profiles are excluded outright without anyone mentioning it at the initial contact.
Knowing the real mortgage conditions for non-residents in Andorra before starting a property search avoids the most frequent mistake: finding the right property and discovering later that the financing does not cover what is needed to close the transaction.
Which banks operate in Andorra and finance non-residents
The Andorran banking system is made up of five main entities regulated by the Andorra Financial Authority (AFA). Of these, the ones that usually work with non-resident profiles in mortgage operations are:
Crèdit Andorrà
One of the entities with the largest presence in the Principality's mortgage market. It works with non-residents on a regular basis, although the risk analysis is more exhaustive than for residents. It requires prior banking attachment with the entity before approving the mortgage.
MoraBanc
Active in the international client and upper-middle-net-worth segments, their conditions for non-residents usually require a demonstrable wealth relationship with the bank prior to granting.
Andbank
Specialised in private banking and wealth management. His non-resident mortgage profile is geared towards high-value transactions, usually linked to clients with assets managed by the institution.
Information on mortgage products and updated conditions can be consulted via the Andorran Financial Authority, supervisory body of the banking system of the Principality.
What really changes if you are not a resident
Here is the specific difference that no bank details on its website until the process begins:
Funding percentage
Residents in Andorra can access financing of up to 80% of the valuation under standard terms. For non-residents, the usual ceiling is between 60% and 70% of the valuation, not the purchase price. If the valuation is lower than the agreed price — which is common in tight markets — the percentage is applied to the valuation, not to the amount you have agreed to pay.
In a transaction worth €500,000, a non-resident with 65% financing based on a valuation of €480,000 receives €312,000. The difference up to the purchase price — €188,000 — must be contributed from their own funds, plus purchase costs of 4–7% of the total price.
Maximum deadline
Mortgage terms for non-residents are usually shorter than for residents. The usual maximum ranges between 15 and 20 years, compared to the 25–30 years accessible to resident profiles with an Andorran payslip.
Interest rate
Andorra does not belong to the eurozone, but its rates are referenced to Euribor or to fixed rates agreed with each institution. For non-residents, the spread applied to the reference index is usually higher than for residents, reflecting the greater risk perceived by the institution.
Bank documentation requirements: the real list
This is the documentation that Andorran banks request from non-residents during the mortgage analysis phase. Having it ready before starting the process speeds up the timeline by 3 to 6 weeks:
Personal documentation
- Valid passport or ID card of all holders
- Certificate of tax residence in the country of origin
- Declaration of source of funds — a commonly underestimated document that may require documentary justification for the last 2–3 years
Financial documentation
- Last three income tax returns or equivalent in the country of origin
- Bank statements from the last 6–12 months for all accounts
- Documentation of other real estate or investment assets if they are claimed as additional collateral
- Current employment contract or, if self-employed, accounting documentation for the last 2 financial years
Property documentation
- Simple Land Registry certificate of Andorra
- Valuation commissioned by the bank (not the seller's one)
- Promise of sale or deposit contract — at this stage, the payment is usually required booking confirmed before starting the full analysis
If an Andorran bank starts the mortgage process without requesting the declaration of origin of funds from the first contact, that requirement is likely to appear at an advanced stage of the process and cause delays. It is advisable to anticipate it from the beginning.
Three mistakes that block the mortgage before it even starts
In Andorra, the quality property market moves fast. Starting your search without a written agreement in principle from a bank means negotiating without knowing your actual budget. Pre-approval does not guarantee the final mortgage, but it defines the viable operating range.
The bank valuation may differ from the price agreed with the seller. In markets like Escaldes-Engordany o Andorra la Vella, where demand exceeds supply, selling prices frequently exceed bank valuations. That difference is covered by the buyer.
Most institutions require the buyer to have an open account with them before granting the mortgage, and the opening process for non-residents can take between 4 and 8 weeks due to regulatory compliance requirements. Starting this procedure in parallel with the property search, rather than after finding it, saves that time.
Mortgage and residency: the most frequent combination among international buyers
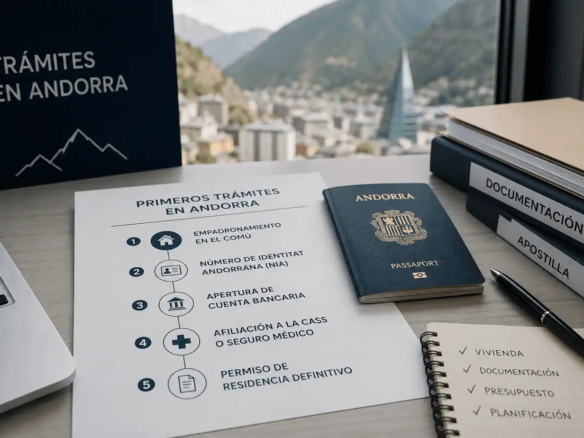
Many non-resident buyers seeking bank financing in Andorra do so within the context of a passive residency through real estate investment. It is worth bearing in mind that the minimum investment required for passive residency — €400,000 free of encumbrances according to the regulations of the Immigration Department of the Government of Andorra — it refers to the mortgage-free value, not the total purchase price.
This means that a property acquired for €600,000 with an outstanding mortgage of €250,000 counts as an investment of €350,000 for the purposes of the residency procedure, falling below the minimum threshold required.
The next step
With the total budget available — own funds plus estimated financing — and the target area defined, the team of shopping service Filter only viable properties within the actual operating range, including the costs associated with the purchase. By sharing the maximum amount of own funds, the priority area, and three essential property criteria, the selection returned is already adjusted to what the bank can finance.
Frequently asked questions about mortgages for non-residents in Andorra
What percentage of funding do Andorra's banks provide to non-residents?
Usually between 60% and 70% of the valuation, compared with the 80% that a resident can obtain under standard conditions. This percentage is calculated on the basis of the valuation carried out by the bank, which may be lower than the price agreed with the seller.
How long does it take to get a non-resident mortgage approved in Andorra?
With the complete documentation prepared in advance, the process can be expedited by 3 to 6 weeks compared to submitting it incompletely or progressively. The total timeframe also depends on the opening of the bank account, which can take between 4 and 8 weeks for non-residents.
Can you apply for a mortgage in Andorra without being a resident?
Yes. Institutions such as Crèdit Andorrà, MoraBanc and Andbank routinely work with non-residents, although they require prior banking ties, greater financial documentation and apply more conservative financing percentages and terms than for residents.